What is the market overview of the Coated Engraved And Heat Treated Metal Products Market?
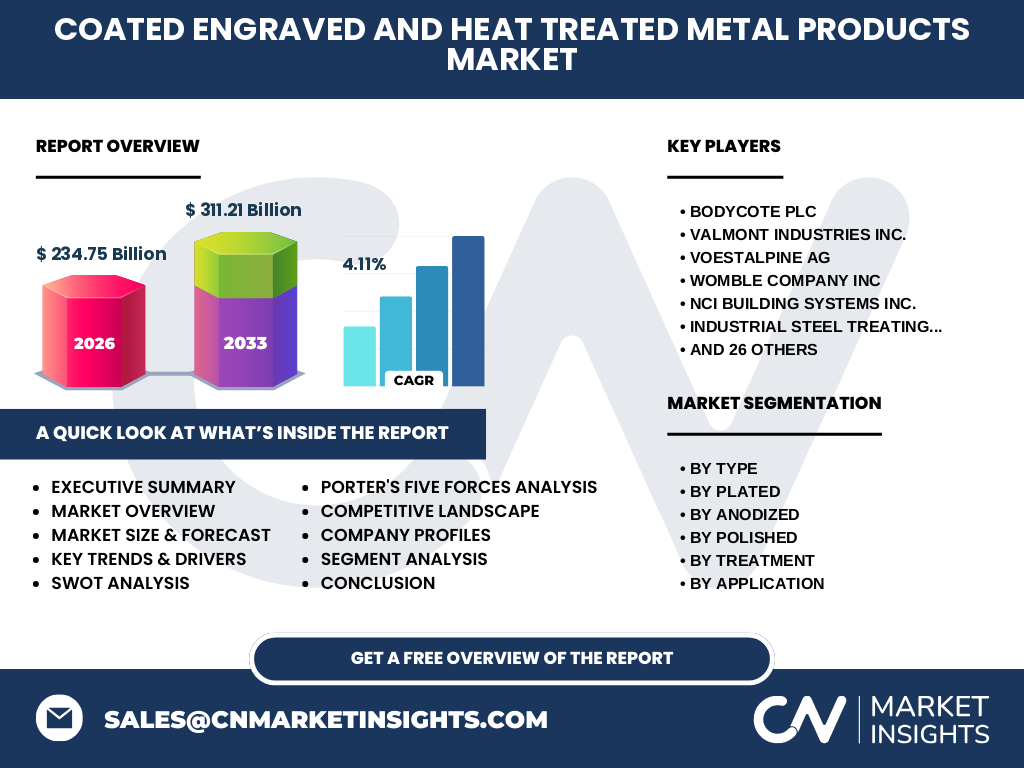
Our analysis indicates that the Coated Engraved And Heat Treated Metal Products Market reached $234.75 Billion in 2026. This foundational sector encompasses vital industrial treatments—including thermal processing, precision engraving, and advanced surface finishing—essential for enhancing the durability, corrosion resistance, and performance of structural components across heavy machinery and precision engineering supply chains globally.
What are the structural growth drivers, restraints, challenges, and opportunities shaping the market?
The market is propelled by stringent automotive lightweighting demands and surging aerospace requirements for wear-resistant alloys. However, our research highlights persistent headwinds from volatile industrial gas pricing and strict environmental compliance mandates governed by agencies like the EPA. Opportunities abound in proprietary nano-coating technologies and automated laser etching integrations.
Emerging trends and growth patterns in the Coated Engraved And Heat Treated Metal Products Market
The industry is witnessing an accelerated shift toward eco-friendly, zero-VOC powder coatings and advanced vacuum heat-treating methods. Leaders like Bodycote plc and Aalberts Industries N.V. are pioneering digital-first metallurgical profiling to optimize quenching and tempering cycles, directly addressing demand for ultra-high-strength components in renewable energy infrastructure.
How did the COVID-19 pandemic impact the industry and shape its recovery trajectory?
Pandemic-induced supply chain disruptions caused sharp contractions in automotive and manufacturing off-take during 2020. Based on our research, the recovery trajectory has been robust, driven by post-pandemic infrastructure stimulus packages and critical supply chain reshoring that heavily favored established regional players like Valmont Industries Inc. and ArcelorMittal.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a mix of multinational metallurgical giants and specialized regional job shops. Market concentration is moderate, with conglomerates like Voestalpine AG leveraging integrated supply chains, while specialized entities such as Industrial Steel Treating Company compete through rapid-turnaround localized services and proprietary metallurgical know-how.
Executive summary of key findings for the Coated Engraved And Heat Treated Metal Products Market
Our comprehensive evaluation confirms a projected market expansion from $234.75 Billion in 2026 to $311.21 Billion by 2033, registering a solid 4.11% CAGR. Growth is anchored by technological advancements in anodized aluminum and specialized laser engraving, underpinning the sector's critical role in modern manufacturing value chains.
What does the market forecast reveal from 2027 to 2033?
The data suggests steady, compounding expansion, lifting the global valuation from 2026 baseline figures of $234.75 Billion to reach $311.21 Billion by 2033 at a 4.11% CAGR. This trajectory is fueled by rising consumption of high-specification galvanized and heat-treated steels across emerging industrial corridors in Asia-Pacific and North America.
Segmentation analysis across product types and application categories
The industry spans diverse segments categorized by type, treatment, and application. Key segments include Heat Treated Metal Products, Coated Metal Products, and Engraved Metal Products And Allied Services To Manufacturers. These serve vital end-use applications in heavy manufacturing and automotive sectors requiring specialized chrome, zinc, or anodized finishes.
Regional market analysis and geographic distribution performance
Geographic performance is heavily weighted toward industrial manufacturing hubs in North America, Europe, and Asia-Pacific. Regional variances are dictated by local environmental regulations and the concentration of automotive OEMs. Asia-Pacific dominates volume consumption, whereas North America and Europe lead in high-margin specialized aerospace and medical device treatments.
In-depth regional review of key manufacturing and consumption corridors
Our analysis of regional corridors reveals that North America and Europe maintain technological leadership in advanced vacuum treatments and eco-friendly electroplating. Meanwhile, rapid industrialization in emerging Asian economies drives massive baseline demand for standard galvanized and color-coated steel products produced by regional giants like Rizhao Steel and Baotou Steel.
Company profiles and strategic positioning of leading market participants
Industry leaders utilize distinct competitive strategies to capture market share. Bodycote plc focuses on specialized thermal processing services, while Valmont Industries Inc. leverages infrastructure-focused coating solutions. Entities like Voestalpine AG and ArcelorMittal integrate coating and heat-treating capabilities directly into their primary steel manufacturing workflows for maximum efficiency.
Porter's Five Forces analysis of competitive intensity
Porter's framework reveals moderate-to-high rivalry driven by fragmented regional job shops competing on turnaround times. Supplier power remains moderate due to raw material price fluctuations for zinc and nickel, while threat of substitutes is mitigated by the irreplaceable mechanical properties imparted by professional heat treatment and specialized coatings.
SWOT analysis of the Coated Engraved And Heat Treated Metal Products Market
Strengths include deeply embedded supplier relationships and essential technical utility. Weaknesses involve high energy consumption during thermal processing. Opportunities lie in electric vehicle lightweighting components, while threats stem from tightening environmental waste regulations governing chemical etching and electroplating effluent management.
Value chain analysis from raw materials to end-users
The value chain originates with raw metal extraction, progressing through rolling mills, and into specialized finishing houses performing spheroidizing, laser engraving, or powder coating. Value is maximized downstream where precision-treated components are integrated into complex manufacturing assemblies by Tier-1 automotive and industrial machinery suppliers.
Investment insights and high-potential growth areas
Strategic investors should target automated laser engraving facilities and proprietary eco-friendly anodizing operations. Our research indicates that capital allocation toward green-tech thermal processing—specifically energy-efficient induction hardening and zero-discharge electroplating—offers superior long-term yields as regulatory pressures escalate across global manufacturing markets.
Conclusion and key takeaways for industry stakeholders
The Coated Engraved And Heat Treated Metal Products Market demonstrates resilient fundamentals, poised to expand to $311.21 Billion by 2033. Success in this landscape requires rigorous operational efficiency, adherence to emerging environmental mandates, and strategic investment in advanced surface engineering technologies to capture high-margin industrial contracts.
Research methodology for baseline estimates and forecast triangulation
Our methodology triangulates baseline estimates by synthesizing proprietary trade registry data, primary stakeholder interviews with metallurgical engineers, and secondary macroeconomic indicators. This multi-tiered approach reconciles raw material consumption metrics with regional manufacturing output to ensure highly accurate market sizing and growth projections.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market dynamics for coated, engraved, and heat-treated metal products through 2027 to 2033. Limitations include unpredictable geopolitical shifts impacting raw material logistics and sudden energy tariff fluctuations that may temporarily skew short-term pricing models for intensive thermal processing operations.
Recent developments, corporate announcements, and strategic industry moves
Recent strategic moves emphasize capacity expansions and sustainability initiatives. Major industry participants have announced targeted joint ventures focused on developing closed-loop water recycling systems for electroplating plants and deploying AI-driven optical sensors for real-time quality control in high-speed CNC engraving lines.